
CURRENT AFFAIRS | 21 SEPTEMBER 2026
India has managed to secure enough urea and liquefied natural gas to keep its nitrogen fertiliser plants running through a year of war-driven energy shocks. But a less visible input has now become a problem: sulphur. In a front-page report on 21 September 2026 (datelined New Delhi, 20 September), The Indian Express’ Harish Damodaran reported that the landed price (cost plus ocean freight) of sulphur imported into India has doubled since the start of 2026 to $1,050–1,100 per tonne. The newspaper’s chart of average import prices shows roughly $1,070 per tonne in September 2026, against about $322 in September 2025 — more than a threefold rise in a year.
The reason, according to the report, lies in attacks on energy infrastructure: Ukrainian long-range drone and missile strikes on Russian oil refineries and gas complexes, and Iranian strikes on the facilities of Saudi Aramco, QatarEnergy and the Abu Dhabi National Oil Company. Because most of the world’s sulphur is recovered at refineries and gas plants, a war on energy sites is also a war on sulphur supply. The consequence for India is serious: sulphur is the starting point of the chain that makes di-ammonium phosphate (DAP), single super phosphate (SSP) and the popular complex fertilisers that farmers depend on.
Why sulphur matters for fertilisers
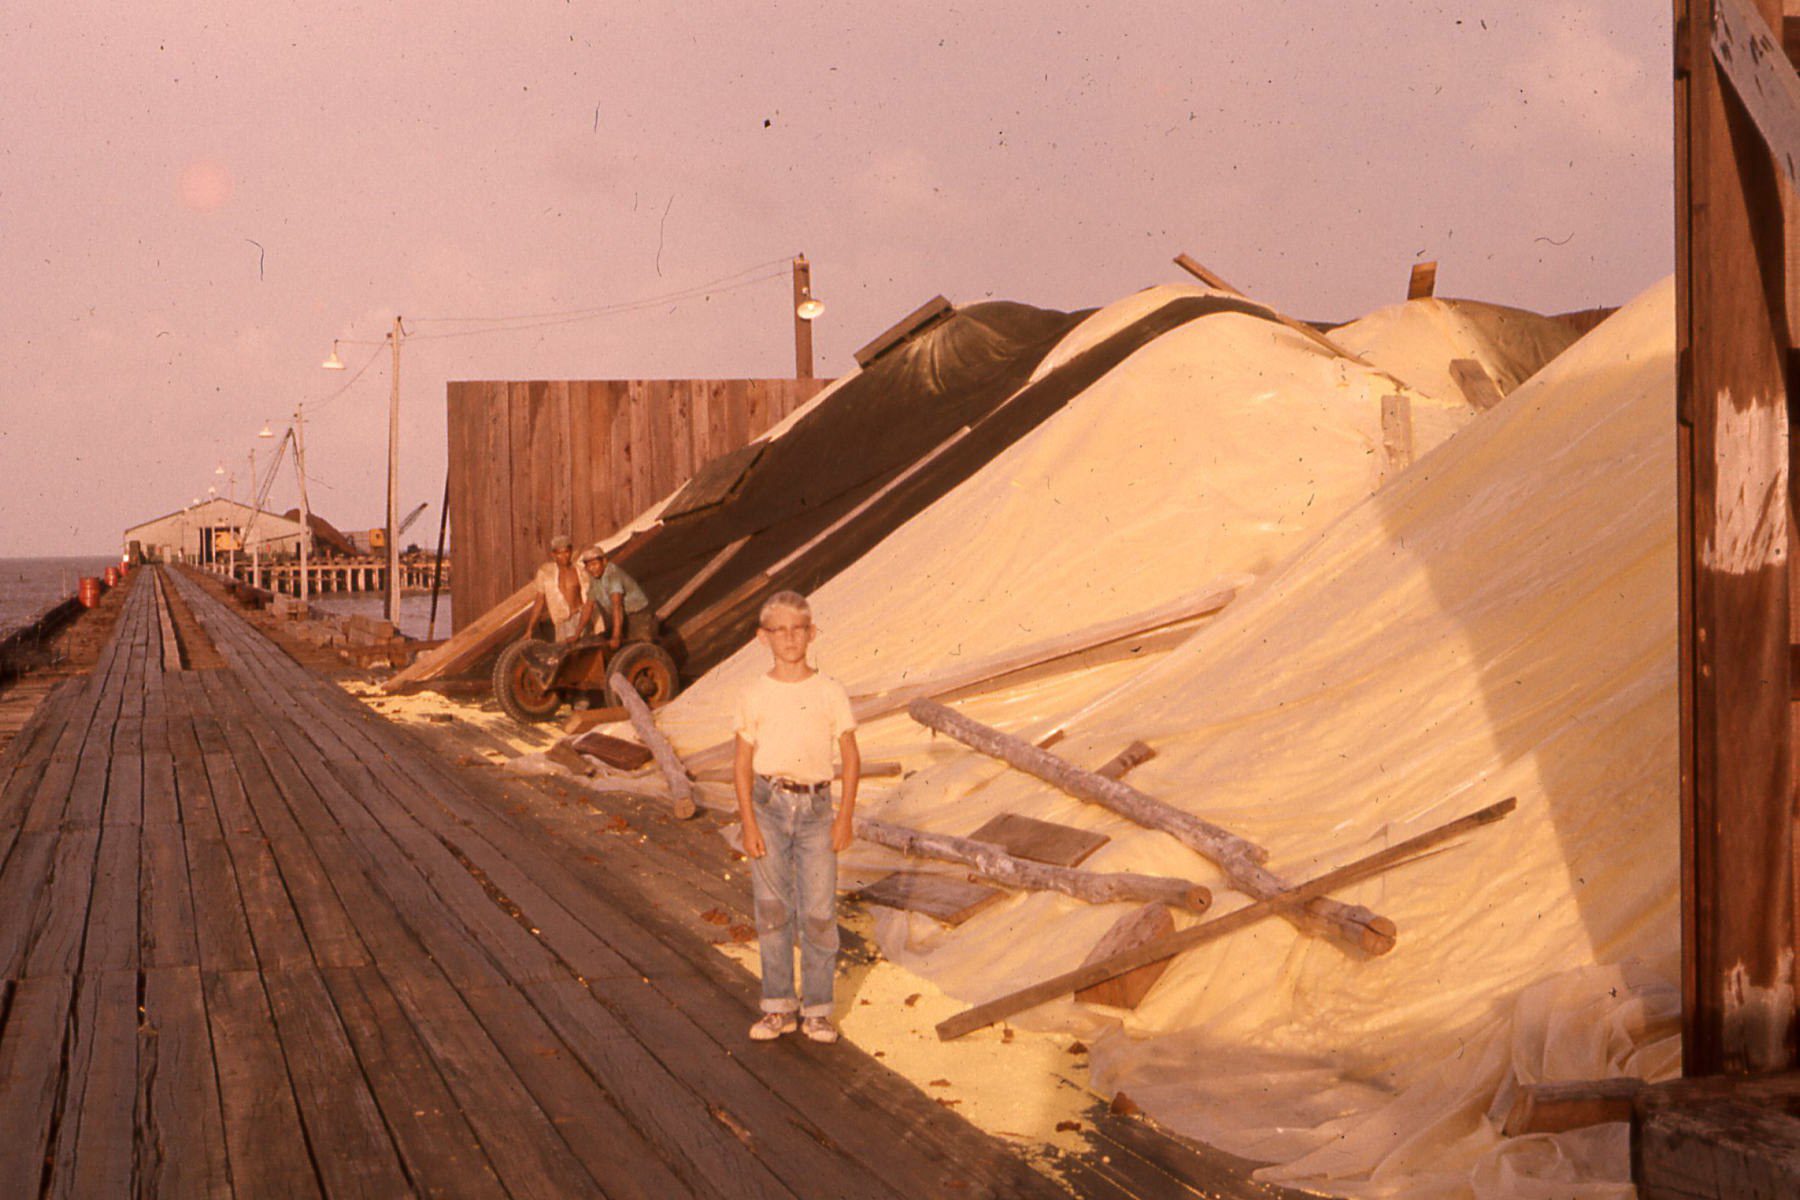
According to the Express report, only about a tenth of the world’s sulphur is directly mined. The rest is a by-product — about 56% from petroleum refining and 34% from natural gas processing — recovered because environmental rules require desulphurisation of crude oil and raw gas to produce cleaner fuels. The fertiliser sector accounts for roughly 60% of the world’s annual sulphur consumption of about 70 million tonnes.
The chemistry explains the dependence. Most sulphur is converted into sulphuric acid. The primary source of phosphorus (P) is rock phosphate, but that mined ore cannot be used as fertiliser until it is broken down into a water-soluble form that plants can absorb — and that is done by reacting it with sulphuric acid. The reaction yields SSP directly, or phosphoric acid, which is then used to make DAP and high-phosphorus complex grades such as 10:26:26 and 12:32:16. As an industry official quoted by the paper put it, without sulphur and sulphuric acid there can be no DAP, SSP or popular complex fertilisers.
India’s own sulphur consumption is 3.8–3.9 million tonnes a year, of which the fertiliser industry uses 2–2.1 million tonnes, the report says. Companies such as IFFCO, Coromandel International and Paradeep Phosphates run integrated plants that import sulphur and rock phosphate; some sulphur comes from domestic refineries and some sulphuric acid from the zinc and copper smelters of Hindustan Zinc and Birla Copper, but the bulk is imported. India’s domestic phosphoric acid capacity of around 2.2 million tonnes meets only about half of its requirement of 4.3–4.5 million tonnes for 15–16 million tonnes of phosphatic fertiliser production.
How sulphur prices got here
The Express traces the price history. Sulphur, a by-product, used to be imported at well below $200 a tonne — even below $100 in many months of 2019 and 2020. Prices rose to $400–500 during March–June 2022 after Russia invaded Ukraine, then fell back below $200 from late 2022 to early 2025. The real trouble began with Ukraine’s intensified strikes on Russian refineries from around August 2025; landed prices crossed $500 by December and climbed further after the US–Iran war. The industry official quoted put current prices of sulphur and sulphuric acid at about $1,070 and $330–350 per tonne, having touched $1,150 and $420 two months earlier.
Two further pressures compound the squeeze. On supply, the paper reports that Russia has banned exports of sulphur and sulphuric acid to protect its own fertiliser industry, and China has restricted exports of sulphuric acid. On demand, the energy transition is competing for the same acid: sulphuric acid is used to extract nickel from laterite ores through high-pressure acid leaching (HPAL), producing mixed hydroxide precipitate for electric-vehicle batteries. Nickel-related acid demand rose from 3.5 million tonnes in 2021 to 16 million tonnes in 2025, much of it in Indonesia, which holds the world’s largest nickel reserves.
Background & Framework
Nutrient Based Subsidy (NBS). Since 1 April 2010, phosphatic and potassic (P&K) fertilisers have been subsidised under the NBS scheme of the Department of Fertilizers (Ministry of Chemicals and Fertilizers). The Centre fixes a per-kg subsidy for four nutrients — Nitrogen (N), Phosphate (P), Potash (K) and Sulphur (S) — every season, and companies receive subsidy according to the nutrient content of each grade. For Kharif 2026 (1 April–30 September 2026), the Union Cabinet on 8 April 2026 approved about ₹41,534 crore for P&K fertilisers, with rates of ₹47.32/kg for N, ₹52.76/kg for P, ₹2.38/kg for K and ₹3.16/kg for S, covering 28 grades; the retail price of DAP was held at ₹1,350 per 50-kg bag. Urea is outside NBS: its maximum retail price is fixed by the government.
Legal controls. Fertilisers are declared an essential commodity under the Essential Commodities Act, 1955. Under that Act the Centre issued the Fertiliser (Control) Order, 1985, which regulates the quality, manufacture, sale, pricing and distribution of fertilisers. Section 3 of the ECA lets the government control production, supply and distribution of any essential commodity.
The policy dilemma
The sulphur spike exposes a structural weakness in India’s fertiliser economy. Because the retail price of DAP is held steady for farmers, rising input costs fall on the subsidy bill or on company margins. The Kharif 2026 NBS rates are valid only until 30 September, so the Rabi 2026–27 rates the government sets next will show how much of the new cost it chooses to absorb. If subsidy lags cost, manufacturers produce or import less, and availability of DAP and complex fertilisers can tighten just as the rabi sowing of wheat, mustard and pulses begins.
There is also an agronomic angle. For years, experts have warned that Indian soil nutrient use is skewed: the fixed low price of urea encourages over-use of nitrogen relative to phosphorus and potassium. NBS was meant to correct that by linking subsidy to nutrient content. A shortage of phosphatic fertilisers could worsen the imbalance, since farmers may substitute with more urea. Balanced fertilisation — including sulphur itself, which Indian soils increasingly lack — is a stated policy goal that price shocks make harder to reach.
In the longer term, the story strengthens the case for diversifying supply (the report notes that IFFCO, Coromandel and Paradeep Phosphates have secured rock phosphate through joint ventures or tie-ups in Jordan, Senegal and Morocco), for recovering more sulphur and sulphuric acid domestically from refineries and smelters, and for strategic stocks — though sulphur, being flammable, cannot be stored for long.
The CLAT Angle
This report is ideal material for a CLAT GK or Current Affairs passage because it links geopolitics, chemistry and economic policy. Likely questions: which fertiliser subsidy scheme covers DAP (NBS, since 2010); which four nutrients carry an NBS rate (N, P, K, S); why sulphur is needed for phosphatic fertilisers (to make sulphuric acid, which converts rock phosphate into soluble form); under which law the Fertiliser (Control) Order, 1985 was issued (Essential Commodities Act, 1955); and what HPAL is used for (nickel extraction for EV batteries). A classic trap: urea is not under NBS. In Logical Reasoning, the passage supports cause-and-effect questions — e.g., why attacks on oil refineries raise fertiliser costs — and assumption questions about whether a fixed retail price protects farmers from input shocks.
Key Facts
- Price: landed sulphur import price $1,050–1,100/tonne, doubled since the start of 2026; ~$1,070 in Sept 2026 vs ~$322 in Sept 2025 (Indian Express).
- Cause: strikes on Russian refineries and gas complexes, and on Gulf energy sites of Saudi Aramco, QatarEnergy and ADNOC.
- Source of sulphur: ~10% mined; ~56% from oil refining and ~34% from gas processing.
- Global use: ~70 million tonnes a year; fertilisers ~60%.
- India’s use: 3.8–3.9 mt a year; fertiliser industry 2–2.1 mt; bulk imported.
- Phosphoric acid: domestic capacity ~2.2 mt vs requirement 4.3–4.5 mt.
- Export curbs: Russia on sulphur and sulphuric acid; China on sulphuric acid.
- EV link: nickel HPAL acid demand rose from 3.5 mt (2021) to 16 mt (2025), largely in Indonesia.
- NBS: since 1 April 2010; Kharif 2026 outlay ~₹41,534 crore; S rate ₹3.16/kg.
- DAP retail price: held at ₹1,350 per 50-kg bag; DAP grade is 18:46:0 (N:P:K).
- Law: Fertiliser (Control) Order, 1985 under the Essential Commodities Act, 1955.
Memory Hook / Mnemonic
Remember the chain as “Refinery → Sulphur → Acid → Rock → DAP”, or simply “No S, no P.” For the subsidy, “NBS pays for N-P-K-S, but never for urea’s U.” And for the law: “’55 makes it essential, ’85 keeps it in control.”
Practice Quiz — 10 CLAT-Style Questions
Click an option to reveal the answer and explanation.